
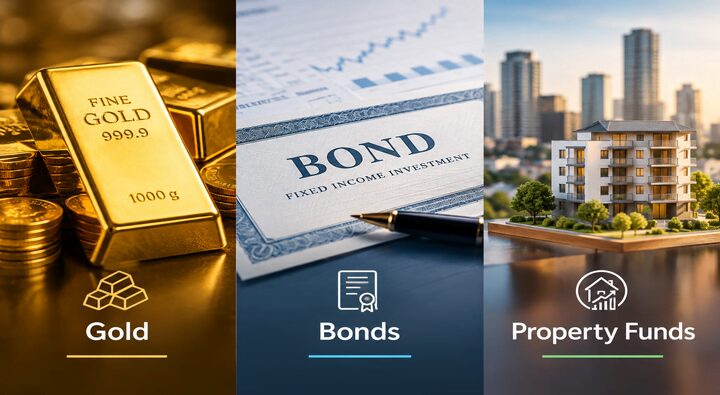
Most people with a stocks and shares ISA have heard the same line about spreading risk. Good advice, no doubt. But it usually ends right there, with no real explanation of what to buy, how to buy it, what it costs, or how any of it will actually perform when the rest of your differently. For each, we’ll cover the cheapest route in through an ISA and flag the catches, including a liquidity trap that left some property fund investors locked out of their own cash for over a year.
What Gold Actually Does for a Portfolio
Gold broke through $5,500 an ounce in January for the first time ever, then gave back a big chunk of those gains over spring and summer. That tells you something. It pays no income, it doesn’t grow, and the price depends entirely on what people will pay for a safety net at any given moment.
That’s the whole point of having it. When shares crash hard, gold tends to come out the other side well ahead of equities, and it finished both 2008 and 2020 up while stock markets posted heavy losses. Expect a few rough weeks along the way, though. In the worst moments of both crashes, gold briefly sold off too as investors dumped whatever they could to raise cash. Think of it as protection across a downturn rather than a shield for every single bad day, and keep the allocation somewhere between 5% and 10% of your portfolio.
Bonds and Gilts Finally Pay You Something
For most of the 2010s, lending money to the UK government paid almost nothing. That changed in 2023. The Bank of England hiked Bank Rate to 5.25%, and gilts became interesting again practically overnight. Rates have come back down since, with the Bank holding
<p>Most people haven’t started yet. The FCA’s
